

U.S. Families: 3 Rules to Make LTC Insurance Pay for Home Care
Yes, most modern long-term care insurance covers home care, not just nursing home stays. Comprehensive policies, now the industry standard, let you use benefits for care at home, adult day care, or assisted living under one shared pool. You’ll typically qualify once you need help with two of six daily living activities, or have a severe cognitive impairment, and you’ll wait through an elimination period before payments start. Always check your policy schedule for daily or monthly limits.
Table of Contents
- What Types Of Long Term Care Plans Cover Home Care?
- How Do Benefits Actually Get Triggered And Paid?
- What Does Home Care Cost, And How Far Will Coverage Stretch?
- How Do You Actually Use A Policy To Pay For In-Home Care?
- How Should You Choose A Policy For Home Care Priorities?
- Can Medicare, Medicaid, Or VA Benefits Fill The Gaps?
- Why Documentation Habits Matter More Than People Realize
- How CareBuilders At Home Supports Families Using LTC Benefits
- Where To Verify Benefits, State Rules, And Costs
- Sources
- FAQ
What Types Of Long Term Care Plans Cover Home Care?
If you’re comparing long term care plans right now, the biggest fork in the road isn’t price. It’s whether the policy is comprehensive or facility-only. Facility-only contracts, common in older policies written decades ago, pay only when someone moves into a nursing home. Comprehensive policies, which dominate the market today, cover care at home, adult day programs, assisted living, and nursing facilities from the same benefit pool, according to the Administration for Community Living. If your parents bought a policy in the 1990s, it’s worth a phone call to the carrier to confirm which type they actually hold.
Within comprehensive coverage, you’ll also see two structural families: stand-alone (traditional) LTC policies and hybrid policies bundled with life insurance or annuities. Hybrids often require a larger upfront premium or a lump sum, but they come with guaranteed premium stability and a death benefit if long-term care is never needed, a trade-off SmartAsset breaks down in detail. Traditional stand-alone policies tend to cost less upfront but carry more exposure to future premium increases.
Home-care benefit amounts also vary by design. Some policies pay the same daily benefit whether care happens at home or in a facility. Others reduce the home-care benefit to a percentage of the facility rate, sometimes significantly less than the full facility rate. Riders for inflation protection and care coordination can change the real value of a policy significantly over a 10 or 20 year horizon.
When you’re weighing options for affordable home care coverage, keep these trade-offs in view:
- Comprehensive policies cost more than facility-only plans but protect you from a coverage gap you won’t discover until it’s too late.
- Hybrid policies suit people who want guarantees and dislike the “use it or lose it” feeling of traditional insurance, though Morningstar notes they carry real opportunity costs.
- A reduced home-care benefit percentage can quietly shrink your coverage exactly when you need it most.
- Inflation riders cost more now but protect purchasing power decades from now, when care costs will be considerably higher.
How Do Benefits Actually Get Triggered And Paid?
Two mechanisms decide when your policy starts paying and how the money reaches you. Understanding both before a health crisis saves you weeks of frustration later.
Benefit eligibility usually hinges on ADL and cognitive triggers. You typically qualify when a licensed health professional certifies that you need substantial help with at least two of six activities of daily living, such as bathing, dressing, toileting, transferring, continence, and eating, or when you have a severe cognitive impairment like advanced dementia, according to the NAIC Shopper’s Guide to Long-Term Care Insurance. Many carriers expect this condition to be chronic, generally lasting or expected to last at least 90 days.
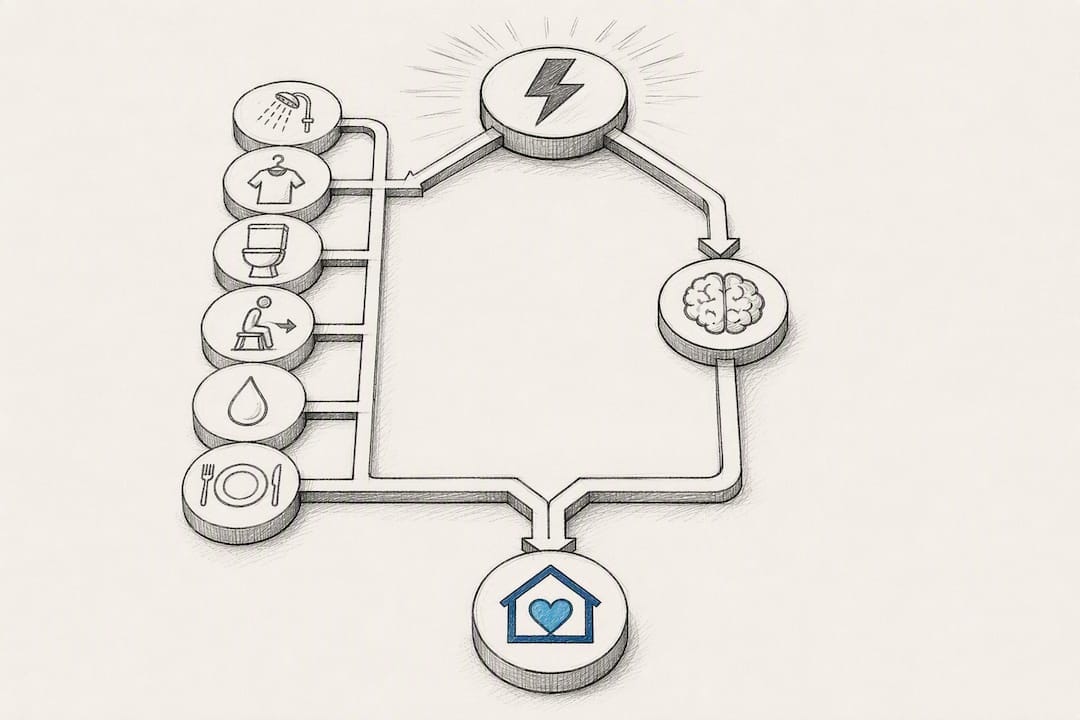
Once you’re certified, the elimination period kicks in. This works like a deductible measured in days, not dollars, and it’s one of the most misunderstood parts of any policy. Some contracts count every calendar day toward satisfying the waiting period, while others only count days when you actually received and paid for care. That distinction alone can add weeks to your out-of-pocket window.
Here’s the practical sequence most families walk through:
- A physician or care assessor certifies the ADL or cognitive trigger and documents a plan of care.
- The elimination period begins, calendar-day or paid-care-day depending on your contract language.
- Once satisfied, the insurer starts paying, either as reimbursement for licensed provider bills or as a cash indemnity benefit you can direct yourself, per the NAIC guide.
- Reimbursement policies typically require invoices from a licensed home care agency; cash indemnity policies often allow payment to family caregivers directly.
Pro Tip: Call your carrier before a crisis hits and ask, in writing, whether your elimination period counts calendar days or only paid-care days. That single question can mean the difference between a 90-day wait and a 130-day wait.
What Does Home Care Cost, And How Far Will Coverage Stretch?
Home care in the United States isn’t cheap, but it’s almost always less expensive than a nursing facility, which is exactly why insurers built comprehensive coverage around it. A state insurance shopper’s guide notes that even part-time home aide visits, a few hours a day, several days a week, add up to thousands of dollars annually, and near-round-the-clock care multiplies that figure many times over.
The math that actually matters is how your daily benefit and benefit period translate into real coverage. If your policy pays $150 a day and your home care runs $200 a day for eight hours of help, you’re covering the gap out of pocket, but you’re still protected against the far larger cost of 24-hour care later. A benefit period measured in years at a fixed daily amount creates a total pool of benefits, which often covers part-time home visits better than extensive daily care.
Inflation is the quiet threat here. Care costs climb every year, and a policy purchased in 2010 without an inflation rider may now cover a shrinking share of actual home care expenses. That’s the real argument for paying more upfront for an inflation-protection rider.
Since almost every policy has an elimination period before benefits start, families need a bridge plan:
- Personal savings or a home equity line, used deliberately, not as an afterthought.
- Medicare, which pays for short-term skilled home health visits under specific conditions, not for open-ended custodial care.
- Medicaid home and community-based services waivers, income and asset limits permitting.
- VA aid and attendance or other veteran-specific in-home supports, where eligible.
How Do You Actually Use A Policy To Pay For In-Home Care?
Turning a policy into an actual paycheck for a caregiver takes more coordination than people expect. Insurers don’t monitor your care automatically. You, or someone acting on your behalf, has to manage the paperwork actively, a point SmartAsset emphasizes for anyone new to filing LTC claims.
Start with these four steps:
- Pull out the actual policy schedule of benefits and confirm home care is covered, then note exactly how it pays: reimbursement or cash indemnity.
- Get physician certification of the ADL or cognitive trigger, plus a documented plan of care, since most carriers require both before the clock starts.
- Confirm whether your carrier demands invoices from a licensed home care agency or will accept payment arrangements with a family caregiver, a detail that varies enormously between reimbursement and cash policies.
- Submit claims promptly with complete documentation, and track every payment against your benefit pool so you know how much runway remains.
If a claim gets denied or delayed, don’t assume it’s final. Request the denial reason in writing, gather any missing documentation (often a more detailed plan of care or updated physician notes), and file a formal appeal through the carrier’s internal process. State insurance department consumer helplines can also intervene when a carrier is unresponsive. Our guide on arranging in-home care for an elderly parent walks through the practical side of setting up services families can then document for insurers.
How Should You Choose A Policy For Home Care Priorities?
If home care coverage is your priority, three things determine whether a policy will actually work when you need it: comprehensive coverage (not facility-only), clear elimination period rules, and the payment structure, reimbursement versus cash indemnity.
Beyond those three, compare policies on:
- Daily or monthly benefit amount, and whether it’s the same for home care as for facility care.
- Total benefit period or lifetime pool amount, since a three-year pool behaves very differently than a lifetime benefit.
- Inflation protection, compound versus simple, which changes how much the benefit is worth in 15 or 20 years.
- Whether family caregivers can be paid directly, which matters enormously if a spouse or adult child plans to provide hands-on care.
- Premium stability history for the carrier, since rate increases have hit older LTC blocks hard industry-wide.
When you talk to an agent, ask directly: “Is this facility-only or comprehensive?” “Does the elimination period count calendar days or paid-care days?” “Can my daughter be paid as a caregiver under this policy?” Vague answers to any of those questions are a red flag. So is contract language that mentions “nursing facility” without ever naming home care explicitly.
Pro Tip: Ask for the policy’s actual definitions page, not the marketing brochure. Terms like “home health care” and “personal care” sometimes carry narrower legal definitions than families assume.
Can Medicare, Medicaid, Or VA Benefits Fill The Gaps?
Long term care insurance rarely operates alone. Medicare covers only limited, short-term skilled home health services after a qualifying hospital stay or physician order, and it generally does not pay for ongoing custodial home care, the kind most families actually need long term.
Medicaid works differently. Through home and community-based services waivers, it can fund substantial in-home support, but eligibility depends on state rules, income limits, and often a spend-down of assets first. Coverage details differ significantly from Texas to any other state.
Veterans may access VA Aid and Attendance or other in-home supports that can run alongside an LTC policy rather than replacing it. Combining sources often makes the most sense:
- Use LTC insurance to cover the elimination period bridge, then draw on Medicaid waivers if the policy pool runs out.
- Layer VA benefits on top of private LTC coverage for veterans who qualify for both.
- Self-fund short gaps with savings while waiting for eligibility determinations on either program.
Why Documentation Habits Matter More Than People Realize
Families tend to think of long-term care insurance as something the carrier manages. In practice, the burden of proof sits almost entirely with the policyholder. Industry data suggests most paid LTC claims are for home-based services rather than facility stays, which means the paperwork problem this article describes isn’t an edge case. It’s the norm.
The gap I keep seeing is between what people expect (“the insurance company will figure it out”) and what actually happens (a family scrambling to find physician certifications and provider invoices while also managing a health crisis). A licensed home care agency that already generates structured invoices, documents visit notes, and coordinates with physicians removes an enormous amount of that friction, particularly for reimbursement-style policies that require licensed-provider billing.
The uncomfortable truth is that a policy with generous benefits and sloppy documentation on the family’s end can still result in delayed or denied claims. The policy language matters, but so does the discipline behind every visit log and invoice.
— cbahplano
How CareBuilders At Home Supports Families Using LTC Benefits
CareBuilders at Home provides non-medical in-home care, including dementia-trained caregivers, companion support, and virtual monitoring, with structured documentation to support reimbursement-based LTC policies. Rather than leaving families to assemble physician certifications and provider invoices alone, our team builds care plans and billing records that align with what insurers ask for.
As a provider, they also help veterans coordinate VA benefits with LTC insurance or private pay to address coverage gaps. If you’re trying to figure out how a policy applies to your situation, start with our personal care services page, or download the free Home Care Navigation Guide for a practical walkthrough of documentation, claims, and coordination steps. Families in the local area can also reach out directly to discuss a loved one’s specific policy and care needs.
Where To Verify Benefits, State Rules, And Costs
- NAIC Shopper’s Guide to Long-Term Care Insurance for trigger and elimination period definitions.
- Medicaid for state-specific waiver rules.
- Eldercare Locator at 800-677-1116 for local Area Agency on Aging referrals.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
Sources
- Administration for Community Living (ACL) — What long-term care insurance covers
- NAIC / Shopper’s Guide to Long-Term Care Insurance
- SmartAsset — Long-term care: elimination periods and policy types
- Medicare
FAQ
What Is The Biggest Drawback Of Long-Term Care Insurance?
Rising premiums over time are the most common complaint, since many older policies have seen significant rate increases as insurers underestimated how long claims would run. The elimination period and strict documentation requirements also catch families off guard when they file their first claim.
Can A 70-Year-Old Get Long-Term Care Insurance?
Yes, but premiums rise sharply with age and some applicants face denial due to existing health conditions. Applying earlier typically secures lower premiums and better underwriting odds.
What Does Dave Ramsey Say About Long-Term Care Insurance?
Dave Ramsey generally recommends buying long-term care insurance once retirement savings are established, rather than earlier or later. He advises against hybrid life insurance products sold primarily as long-term care solutions.
Who Offers The Best Long-Term Care Coverage For Home Care Needs?
There’s no single best national provider. The right policy depends on your state, health history, and whether comprehensive home-care coverage, favorable elimination period terms, and payment structure fit your family’s situation. A licensed insurance agent and a home care provider like CareBuilders at Home of Plano & Allen can help you evaluate specific offers against your actual care plans.
Does Long-Term Care Insurance Cover A Family Member As Caregiver?
Some cash indemnity policies allow payment to family caregivers directly, while most reimbursement policies require licensed agency invoices. Check your policy’s specific language, since this detail varies significantly between contracts.